

What if your passport isn’t the deciding factor in your UK property tax bill? The answer to UK stamp duty for overseas buyers 2026 depends first on where the property is, then on details such as your UK residence history, whether you’re buying alone or jointly, and whether you already own another home. In England and Northern Ireland, a 2% non-resident surcharge may apply to Stamp Duty Land Tax (SDLT). Scotland and Wales have separate property tax systems with their own rules.
It’s understandable to want a reliable figure before making an offer. But overseas-buyer surcharges and residence tests can make a quick estimate misleading, particularly if you’re buying with someone else or purchasing an additional property. For SDLT, the non-resident test is based on days spent in the UK, not simply nationality or visa status.
This guide explains which tax system applies based on the property’s location, which buyer and property circumstances can affect your bill, and what to check before completion. It also covers when transaction-specific legal or tax advice can help confirm your position, so you can budget with greater clarity before committing.
Key Takeaways
- For UK stamp duty for overseas buyers 2026, start with the property’s location: the applicable tax system and calculation vary across the UK.
- Check residence status, joint ownership, property use and existing property ownership before estimating your potential liability.
- Compare your circumstances with the current official tax bands, then ask a qualified professional to confirm the calculation and any surcharges.
- Before completion, verify who must file and pay, the applicable deadline and the rules of the relevant tax authority.
- Property sourcing and transaction coordination can support your purchase process, but they don’t replace qualified tax or legal advice.
UK stamp duty for overseas buyers in 2026: Which tax applies?
First, identify where the property is located. The UK doesn’t have a single property transaction tax with one set of rates and overseas-buyer rules. The applicable system depends on the nation, the transaction date and the details of the purchase, including the buyer and property type. An estimate based on the wrong jurisdiction can therefore be misleading.
SDLT, LBTT, and LTT: the UK property-tax distinction
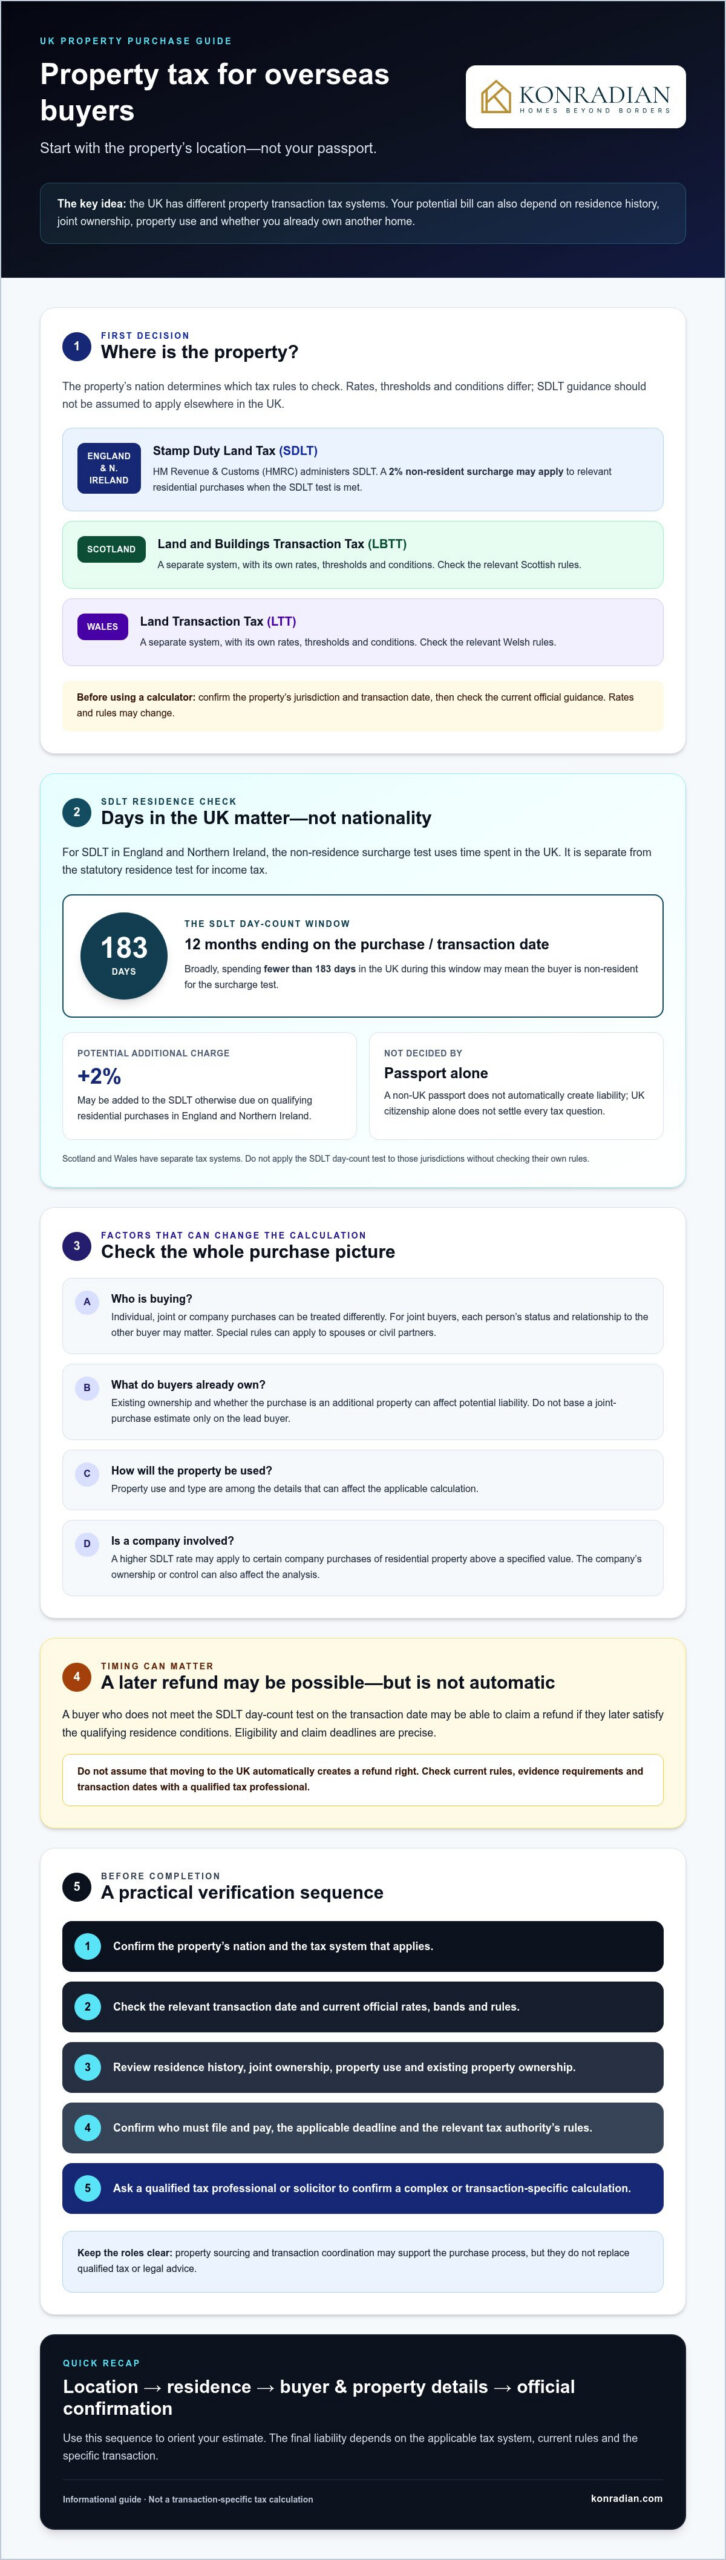
Stamp Duty Land Tax (SDLT) applies to relevant property purchases in England and Northern Ireland. HM Revenue & Customs (HMRC) administers SDLT and provides the rules and guidance for those transactions. Scotland uses Land and Buildings Transaction Tax (LBTT), while Wales uses Land Transaction Tax (LTT). Each system has its own rates, thresholds and conditions, so SDLT guidance shouldn’t be assumed to apply to property elsewhere in the UK.
For a general overview of the history and scope of Stamp Duty Land Tax (SDLT), see the linked summary. Before relying on any figures, check the relevant tax authority’s current guidance for the property’s nation and transaction date. Rate bands and rules may change, and an older calculator or article may not reflect the schedule that applies to a 2026 purchase.
What counts as an overseas buyer?
“Overseas buyer” is a general description, not a single tax status. The surcharge test depends on the rules in the property’s jurisdiction and the buyer’s circumstances. Nationality, where someone usually lives and their tax residence are related but distinct concepts. A non-UK passport doesn’t automatically mean a buyer owes an overseas-buyer surcharge, and UK citizenship alone doesn’t settle every tax question.
For SDLT in England and Northern Ireland, an individual’s non-resident status for the surcharge is determined by a specific day-count test. Broadly, the test considers whether they’ve spent fewer than 183 days in the UK during the 12-month period ending on the purchase date. This is an SDLT-specific test, not the statutory residence test used for income tax. Scotland and Wales have separate tax systems, so check their relevant residence and surcharge rules rather than applying the SDLT test there.
Use this section as an orientation, not as a transaction-specific tax calculation. Before making an offer or completing, confirm the property’s jurisdiction, the relevant date and your circumstances against current official guidance. If your status or ownership structure is complex, ask a qualified tax professional or solicitor to assess the transaction.
How overseas-buyer residence rules can change SDLT
For residential purchases in England and Northern Ireland, a buyer who meets the SDLT non-residence test may pay a 2% surcharge on top of the SDLT otherwise due. This is an additional tax test, not a judgment based on passport or nationality. A non-UK citizen isn’t automatically liable, and a UK citizen may still need to check their residence position. The official government guidance explains the SDLT rules and how the test is applied.
How the SDLT non-residence test may apply
For an individual buying in England or Northern Ireland, the test generally looks at whether they were present in the UK for at least 183 days during the 12 months ending on the transaction date. This window is specific to SDLT. It isn’t the same as asking where you usually live or applying the statutory residence test for income tax.
Timing can matter after completion, too. A buyer who doesn’t meet the day-count test on the transaction date may be able to claim a refund if they later satisfy the qualifying residence conditions. The eligibility period and claim deadline are precise, so don’t assume that moving to the UK automatically creates a right to a refund. Ask a UK tax professional to check the current 2026 test, evidence requirements, reliefs and refund provisions against your travel history and transaction dates.
Joint purchases need careful review. Each buyer’s status and relationship to the other purchaser may affect the calculation, and special rules can apply to spouses or civil partners. Don’t estimate the surcharge based only on the lead buyer’s circumstances.
When buyer structure and property use matter
Who buys the property can change the analysis. An individual purchase, a joint purchase and a purchase through a company may be subject to different rules. For example, a higher SDLT rate may apply to certain company purchases of residential property above a specified value. A company’s ownership or control can also affect surcharge considerations. Check the entity’s structure and transaction details before finalising an offer.
Property use matters as well. Buying an additional dwelling can trigger a separate surcharge from the non-resident surcharge. In England and Northern Ireland, both charges may apply, but whether a property counts as an additional dwelling depends on ownership and transaction circumstances. Scotland and Wales have separate tax regimes, so check their own residence tests, additional-property rules, rates and available reliefs rather than relying on SDLT assumptions.
For a purchase involving cross-border residence, multiple buyers or a company, obtain transaction-specific advice before committing. Property sourcing and acquisition support can help coordinate selection and due diligence, while a qualified tax professional should confirm your liability. If you’re assessing a UK purchase, UK property sourcing and acquisition support may help organise the broader transaction. Confirm the scope and buyer-paid terms directly.
How to compare potential stamp-duty liability before buying
A useful estimate starts with a complete picture of the transaction, not just the purchase price. For UK stamp duty for overseas buyers 2026, check the current official tax-band schedule for the property’s nation and confirm its effective date before calculating. A rate table from another UK nation, or one that applied before the transaction date, may give you the wrong result.
Which details do you need for a reliable estimate?
Gather these details before using a calculator or asking a professional to check the figures:
- Property location, agreed or expected price, intended use and likely transaction date.
- Each purchaser’s residence position and ownership history, including relevant property interests in the UK or abroad.
- Whether the purchase will be in individual names, jointly, or through a company or another entity.
- Any circumstances that could affect reliefs or special rules. Have these assessed rather than assuming they apply.
Then apply the relevant nation’s bands and buyer-specific rules. For England and Northern Ireland SDLT, HMRC’s Official UK Government Guidance on SDLT for Non-Residents explains the non-resident surcharge. Check current guidance again before relying on a 2026 estimate, especially if the transaction date or buyer structure changes.
Why two overseas buyers may owe different amounts
Consider two illustrative purchases at the same price. One buyer is purchasing a home and has no other relevant property interests; the other is buying an additional dwelling. The second buyer may need to account for additional-property rules as well as any applicable residence-related surcharge. The outcome depends on the full circumstances, so these examples show what to check, not a guaranteed tax result.
The same purchase details can also lead to different calculations depending on the nation. SDLT applies in England and Northern Ireland, while Scotland and Wales use their own tax systems and schedules. Don’t transfer an SDLT rate or surcharge assumption to an LBTT or LTT estimate.
| Location | Illustrative buyer and use | Compare before estimating |
|---|---|---|
| England or Northern Ireland | Individual buying a home or an additional dwelling | Current SDLT bands, residence test, ownership history and additional-property rules |
| Scotland | Overseas individual or entity, buying a home or another property | Current LBTT schedule and applicable buyer, use and surcharge rules |
| Wales | Overseas individual or entity, buying a home or another property | Current LTT schedule and applicable buyer, use and surcharge rules |
Location and buyer circumstances can change the applicable calculation. Treat any comparison as illustrative until a qualified UK tax professional has checked the effective rates, transaction date, ownership details and possible reliefs against your circumstances.
Steps Before Completing a UK Property Purchase
A short pre-completion review can prevent an estimate from becoming an avoidable source of uncertainty. For UK stamp duty for overseas buyers 2026, confirm the tax system, buyer status and filing arrangements before committing to the transaction. Use this checklist as a practical guide, then ask a qualified adviser to review any complicated details.
A pre-completion stamp-duty checklist
- Confirm the property’s nation. Establish whether the property is in England, Northern Ireland, Scotland or Wales, and identify the applicable tax: SDLT, LBTT or LTT.
- Confirm the transaction date and buyer details. Gather the expected completion date, purchase price, intended property use, each buyer’s residence information and relevant ownership history. Record whether the purchase will be made jointly or through a company.
- Request a current tax review. Ask a qualified adviser to check the applicable 2026 rates, surcharges, reliefs and filing requirements for that jurisdiction. Residence tests, multiple purchasers, company ownership or possible relief claims warrant particular care. Don’t assume eligibility based on a general online example.
- Organise the transaction file. Keep the sale documents, identity and residence records, ownership information, tax calculations and adviser correspondence together. Clear records help the responsible professional confirm the return and support the position taken.
- Agree who files and pays. Confirm in writing whether your solicitor or conveyancer will prepare and submit the return, arrange payment, or needs you to provide funds or information by a particular date.
Returns, payment, and professional review
For SDLT transactions in England and Northern Ireland, the return must generally be filed with HMRC and the tax paid within 14 days of completion. A solicitor or conveyancer commonly manages these steps as part of the transaction, but confirm the arrangement directly rather than assuming it’s included. Scottish and Welsh purchases follow separate LBTT and LTT processes. Check the current deadline, payment method, responsible party and any penalties with Revenue Scotland or the Welsh Revenue Authority.
Check the process before exchange or completion, not when the deadline is approaching. Ask your adviser which authority applies, what information they need from each purchaser, how payment will be made and what happens if the transaction details change. This is especially important when residence status, an entity purchase, reliefs or several buyers affect the analysis.
For broader context on coordinating legal matters during an overseas property transaction, see international property legal support. Transaction guidance can help organise the process, but a qualified tax professional or solicitor should confirm your specific filing and tax position.
Choosing informed support for an overseas UK property purchase
A clear decision path makes the tax question easier to manage: confirm the property’s location, establish each buyer’s relevant status, estimate the applicable tax, then have the figures and assumptions checked professionally. For UK stamp duty for overseas buyers 2026, that final review matters because the property’s location, ownership structure, intended use and residence circumstances can all affect the analysis.
What a UK property sourcing specialist can help coordinate
A UK property sourcing specialist can help with property selection and acquisition support, and coordinate practical questions that arise during due diligence. This can help you identify what to raise with your solicitor or tax adviser, such as how a proposed ownership structure or residence history may affect the transaction. It doesn’t replace independent legal or tax advice, determine your tax liability, or guarantee a particular investment outcome.
Konradian provides UK property sourcing and acquisition support, including property selection and legal and financial transaction guidance. UK sourcing and acquisition services are charged to the buyer, so ask about the scope and terms, including how buyer-side fees are structured, before proceeding. You can ask about the UK property sourcing and acquisition support service as part of that conversation.
Questions to ask before appointing an adviser
- What does the service include, and what falls outside its scope?
- How are buyer-side fees structured, and when are they payable?
- Who will provide tax and legal advice, and are they appropriately qualified for your transaction?
- Who will confirm the applicable tax system, calculation, return and payment arrangements?
- What information or documents will each adviser need from you and any joint purchasers?
Clear responsibilities help prevent a sourcing or coordination role from being mistaken for a tax opinion. Ask for the proposed scope in writing, and have a qualified professional verify the tax position against the purchase details before you commit. If your circumstances involve multiple buyers, a company, possible reliefs or complex residence history, raise those details at the outset.
If you’re considering a UK purchase and would like to discuss your property requirements, you can speak with Konradian about its buyer-paid sourcing and acquisition support. You don’t need to settle every tax question in that conversation. The aim is to clarify what support you may need and which points should be confirmed independently by qualified advisers.
Make your UK property decision with greater clarity
To estimate UK stamp duty for overseas buyers 2026, start with the property’s location, then consider each buyer’s residence position, ownership history, property use and transaction structure. England and Northern Ireland, Scotland, and Wales follow different tax systems, so check the relevant authority’s current rules and rates for your transaction date.
Use an estimate to plan, not as a substitute for a transaction-specific review. Before committing, ask a qualified tax or legal professional to confirm the calculation, possible reliefs, and who will handle filing and payment. Property sourcing and acquisition support can help coordinate the wider purchase, but it doesn’t replace specialist advice.
Konradian provides UK property sourcing and acquisition support and brings more than five years of international property experience. Its UK buyer-side services are paid, so confirm the scope and terms. If you’re considering a purchase, discuss your UK property requirements with Konradian. With the right checks and support, you can move forward with a clearer plan.
Frequently Asked Questions
Does being an overseas buyer automatically mean I pay an SDLT surcharge?
No. For SDLT purchases in England and Northern Ireland, surcharge liability depends on the applicable residence test and the transaction details, not nationality alone. A non-UK citizen isn’t automatically liable, and a UK citizen may still need to check their residence status. Joint purchases, property ownership and the relationship between buyers can also affect the calculation, so confirm your circumstances against current HMRC guidance.
Does UK stamp duty apply to property purchases in Scotland and Wales?
No. SDLT applies in England and Northern Ireland, not throughout the UK. Property purchases in Scotland are generally subject to Land and Buildings Transaction Tax (LBTT), while Welsh purchases are generally subject to Land Transaction Tax (LTT). Each system has its own rates, surcharges and conditions. Check the official guidance for the nation where the property is located rather than applying SDLT rules across the UK.
How is the non-resident SDLT surcharge assessed for overseas buyers?
For an individual buying residential property in England or Northern Ireland, the SDLT non-residence test generally considers whether they spent fewer than 183 days in the UK during the 12 months ending on the transaction date. This is a specific SDLT test, not a test of nationality or the income-tax statutory residence test. Joint buyers and certain spouse or civil-partner circumstances need careful review under HMRC guidance.
Can a company buying UK property be treated differently for stamp duty?
Yes. Company purchases can be subject to different SDLT rules from individual purchases. A 17% flat SDLT rate may apply to certain residential property acquisitions by companies above £500,000, and a non-resident surcharge may also be relevant in some cases, including for some UK-resident companies controlled by non-UK residents. The outcome depends on the company, property and transaction, so obtain specialist advice before relying on an estimate.
How much stamp duty will an overseas buyer pay in 2026?
There’s no single amount for UK stamp duty for overseas buyers 2026. The bill depends on the property’s nation, price, transaction date, buyer residence status, ownership history and property use. In England and Northern Ireland, the 2% non-resident surcharge may apply, and an additional-property surcharge may also be relevant. Scotland and Wales have separate tax schedules. Use current official rates and have your specific calculation checked professionally.
When must stamp duty be reported and paid after buying UK property?
For SDLT purchases in England and Northern Ireland, the return must generally be filed with HMRC and the tax paid within 14 days of completion. A solicitor or conveyancer commonly handles the return and payment, but confirm who is responsible and when funds or documents are required. Scotland and Wales use separate processes and authorities, so check the current filing and payment deadline for the property’s nation.
Can I reclaim an overseas-buyer surcharge if my residence circumstances change?
Possibly. An SDLT buyer may be able to claim a refund of the 2% non-resident surcharge if they meet the qualifying UK presence test after the purchase. The rules require at least 183 days in the UK during a qualifying continuous 365-day period within the specified window around the transaction, and the claim must be made within two years of the effective date. Check current HMRC requirements and seek professional advice before claiming.
